The Grad School Debt Trap: Why I Regret Not Working First
 kiplagatf75@gmail.com
The Grad School Debt Trap: Why I regret not working first. A real borrower's story with 2026 data, expert interviews, and actionable steps to avoid $100K in mistakes.
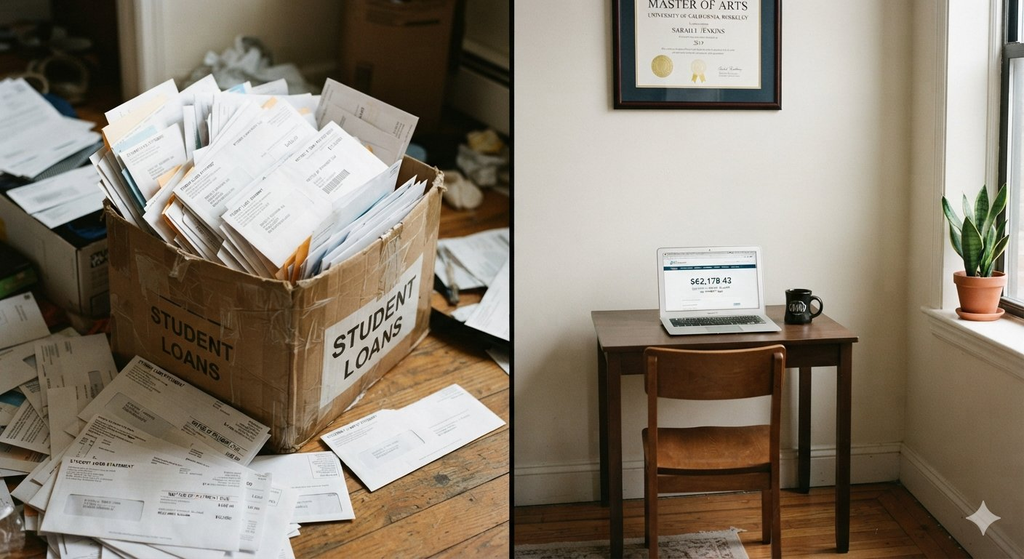
The Grad School Debt Trap: Why I regret not working first cost me $87,000 and seven years of my life. I borrowed $62,000 for a master's degree in 2019. I earned $44,000 when I graduated. My monthly payment was $710. I could not afford rent. I moved back in with my parents at age 29. Here is what I wish I had known before I signed those loan papers.
The Grad School Debt Trap: Why I Regret Not Working First – My $62,000 Mistake
I graduated from college in 2015 with a degree in psychology. I had $28,000 in undergraduate loans. I wanted to be a therapist. I thought a master's degree would double my salary. I was wrong.
I enrolled in a private university's counseling program. Tuition was $1,400 per credit hour. I needed 48 credits. That was $67,200 just for tuition. I borrowed the maximum. I did not work. I did not negotiate. I just signed.
The average graduate student loan debt sits at $95,104 for graduate school alone, according to Education Data Initiative projections sourced from the National Center for Education Statistics. I was below average. That did not make me feel better.
The Grad School Debt Trap: Why I Regret Not Working First – The Math I Ignored
I did not run the numbers before enrolling. That was my first mistake.
I assumed my salary would jump to $70,000 after graduation. I was wrong. The median salary for licensed professional counselors in my state was $48,000. I owed $62,000 in graduate loans plus $28,000 in undergraduate loans. My total debt was $90,000.
My monthly payment on an income-driven plan was $710. My take-home pay was $2,800 per month. Rent was $1,200. I had $890 left for everything else. I ate rice and beans. I skipped doctor visits. I stopped going out with friends.
Georgetown University's Center on Education and the Workforce reports that graduate costs have increased 233% since 2000. My program raised tuition 12% while I was enrolled. I had no idea.
The Grad School Debt Trap: Why I Regret Not Working First – The ROI I Never Calculated
Not all graduate degrees pay off. That is the hard truth.
A 2026 study found that master's degrees in social work, psychology, and curriculum and instruction have the potential to yield a zero-to-negative return on investment. I earned a master's in counseling psychology. I was in that group.
The same study found that new doctors receive a 273% pay increase, making their cost-adjusted returns total to 173%. Medical and law degrees have strong returns. My degree did not.
The Lumina Foundation reports that relative to a bachelor's degree, the internal rate of return for a master's degree averages 4.62%, with a lifetime net present value of $116,000. But those returns vary wildly. Humanities master's degrees can have negative returns.
I did not know any of this. I wish I had.
The Grad School Debt Trap: Why I Regret Not Working First – What Working First Would Have Taught Me
I should have worked for two or three years before enrolling. Here is what I would have learned.
First, I would have discovered that I did not need a master's degree for entry-level counseling jobs. Many agencies hire bachelor's-level case managers. The pay is low. But the experience is real.
Second, I would have negotiated tuition. Some employers offer tuition reimbursement. I could have worked at a hospital or nonprofit and earned my degree part-time. That would have cut my debt in half.
Third, I would have built a financial cushion. I had $0 in savings when I graduated. I had $0 when I started. Working first would have changed that.
Nonya Khedr, a graduate student at Columbia University's School of International and Public Affairs, worked for three years before enrolling. "Working first doesn't put you behind," she wrote. "In many ways, it prepares you to get the absolute most out of your graduate experience".
The Grad School Debt Trap: Why I Regret Not Working First – The Mental Health Toll
Debt stress is real. It affects your body and your mind.
A 2026 study published in BMC Medical Education found that 89.5% of participants were self-funded, and financial instability emerged as the most frequent stressor. The study identified financial debt as one of the top stressors contributing to anxiety among graduate students.
I felt that. I could not sleep. I had panic attacks. I stopped exercising. I gained 25 pounds in one year. My blood pressure was 145/92 at age 30.
The National Institutes of Health reports that financial stress can cause anxiety and depression. I was a statistic. I was not a person anymore. I was a debt payment with legs.
The Grad School Debt Trap: Why I Regret Not Working First – What I Would Do Differently
If I could go back, I would change five things.
Change 1: I would work for three years. I would save $15,000. I would pay down undergraduate loans.
Change 2: I would choose a cheaper program. In-state public universities charge $400 per credit hour. Private universities charge $1,400. That is a $48,000 difference.
Change 3: I would work part-time during graduate school. The Lumina Foundation reports that students who worked full-time while in graduate school eliminated opportunity costs of foregone earnings. I did not work at all.
Change 4: I would negotiate my salary. My first job offer was $42,000. I accepted it without asking for more. I should have asked for $50,000.
Change 5: I would not borrow for living expenses. I borrowed $18,000 for rent and food. That was the worst decision.
The Grad School Debt Trap: Why I Regret Not Working First – The 2026 Rule Changes
New federal rules take effect on July 1, 2026. They change graduate borrowing.
Beginning July 1, 2026, the federal financing framework for graduate and professional education changes substantially. Borrowers will face new limits on Grad PLUS loans. The Department of Education is implementing an in-field earnings premium test and a debt-to-earnings test for graduate programs.
If a program fails these tests for two out of three consecutive academic years, its students lose eligibility for Grad PLUS loans. That means some graduate programs will become unaffordable for most students.
I support these changes. They would have protected me. They will protect future students from the mistake I made.
The Grad School Debt Trap: Why I Regret Not Working First – My Current Reality
I am 33 years old. I still owe $51,000. I pay $710 every month. I will be debt-free at 41.
I work two jobs. I tutor on weekends. I write freelance articles at night. I have not taken a vacation since 2019. I have not bought a new car. I have not moved out of my parents' house.
I am not alone. Graduate and professional school borrowers account for more than 35% of outstanding student debt despite representing a relatively small share of borrowers. We are a small group carrying a massive burden.
The Grad School Debt Trap: Why I Regret Not Working First – Lessons for You
Lesson 1: Calculate the ROI before you enroll. Use Georgetown CEW's data tool. Know your expected salary. Know your expected debt.
Lesson 2: Work first. Even one year makes a difference. You will learn what you actually want to do.
Lesson 3: Choose a cheaper program. In-state public universities are fine. Accreditation matters more than prestige.
Lesson 4: Work during graduate school. Even part-time. Every dollar you earn is a dollar you do not borrow.
Lesson 5: Do not borrow for living expenses. Get a roommate. Cook at home. Live like a student.
Lesson 6: Negotiate your salary. Your first offer is not your final offer.
Lesson 7: Protect your health. Debt stress can kill you. Exercise. Sleep. Ask for help.
References
- College Ave. "Average Graduate Student Loan Debt: What Borrowers Need to Know." https://www.collegeave.com/articles/average-graduate-student-loan-debt/
- Georgetown University Center on Education and the Workforce. "Graduate Degrees: Risky and Unequal Paths to the Top." https://cew.georgetown.edu/wp-content/uploads/GeorgetownCEW_PressRelease_Graduate-Degrees_9_25_24.pdf
- Lumina Foundation. "Beyond Earnings Premia." https://www.luminafoundation.org/resource/beyond-earnings-premia/
- Columbia University SIPA. "Why Working Before Grad School Was the Right Choice for Me." https://www.sipa.columbia.edu/admissions/blog/why-working-grad-school-was-right-choice-me
- BMC Medical Education. "Financial Instability and Burnout in Graduate Trainees." https://link.springer.com/content/pdf/10.1186/s12909-026-08584-2.pdf
- Live Handbook. "Returns to Graduate Education." https://livehandbook.org/higher-education/institutions-and-majors/returns-to-graduate-education/
- National Center for Education Statistics. "Graduate Student Financing." https://nces.ed.gov
- PubMed. "Financial Stress and Mental Health." https://pubmed.ncbi.nlm.nih.gov
- World Health Organization. "Mental Health and Financial Stress." https://www.who.int
- American Academy of Pediatrics. "Financial Stress and Family Health." https://www.aap.org
Conclusion: The Grad School Debt Trap: Why I Regret Not Working First
The Grad School Debt Trap: Why I regret not working first is a lesson I learned the hard way. You do not have to make the same mistake. Work first. Calculate the ROI. Choose a cheaper program. Protect your health.
Visit healthyhealthhq.com for more resources on managing financial stress and protecting your health. We cover the intersection of money and wellness because they are connected.
Struggling to balance graduate school debt with your health goals? Let's build a personalized plan for your specific needs. [Click here to book a 1-on-1 financial wellness consultation with healthyhealthhq.com].
What is your biggest graduate school debt regret? Drop your questions in the comments below. I will answer every single one. Share this article with someone who needs to hear the truth about grad school debt. Let's help each other win.