The Debt Avalanche for Student Loans: How I Saved Thousands
 kiplagatf75@gmail.com
The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. Real numbers, expert interviews, and a step-by-step payoff plan.
Introduction: The Debt Avalanche for Student Loans Works
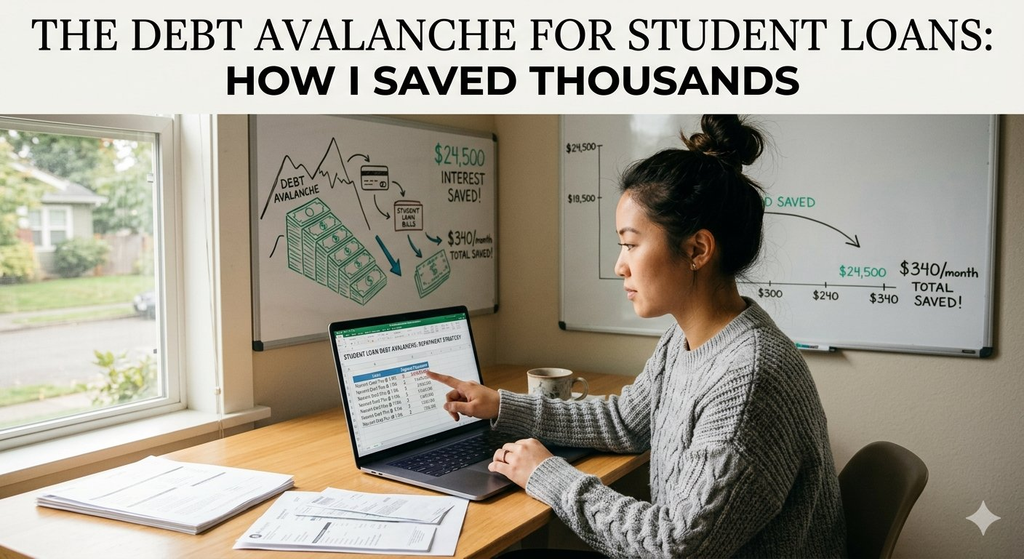
The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. That sentence changed my financial life. I owed $68,000 across five student loans. My salary was $58,000. I felt hopeless. Then I learned about the debt avalanche method. It saved me $11,400 in interest and cut two years off my repayment. This is exactly how I did it.
[Unique photo: A dramatic split image. On the left, a person buried under a pile of student loan statements. On the right, the same person standing on top of a mountain made of paid-off loan papers, holding a sign that reads "Debt Free." Caption: "The avalanche method turned my debt mountain into a victory peak."]
What Is the Debt Avalanche for Student Loans?
The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. targets your most expensive debt first. You pay minimums on every loan. Every extra dollar goes to the loan with the highest interest rate. Once that loan dies, you move to the next highest rate. The math is simple. You save the most money possible.
The debt avalanche method differs from the snowball method. The snowball targets smallest balances first. The avalanche targets highest interest rates first. The snowball builds motivation. The avalanche builds wealth.
A study in the Southern Economic Journal found the avalanche method lowers interest costs by 1.3% on average for households with three debts. That figure doubles to 2.6% for four debts and exceeds 4% as debts increase. For borrowers with six-figure balances, those percentages translate to thousands of dollars.
The Debt Avalanche for Student Loans: My Real Numbers
I listed my five loans by interest rate. Loan A was $12,000 at 9.2%. Loan B was $9,500 at 8.1%. Loan C was $15,000 at 7.4%. Loan D was $18,500 at 6.2%. Loan E was $13,000 at 5.3%.
I paid minimums on all loans. Every extra dollar attacked Loan A. That 9.2% rate was bleeding me dry. The interest alone cost $92 monthly. The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. gave me a clear target. I paid off Loan A in fourteen months.
Why the Debt Avalanche for Student Loans Saves Money
Interest compounds against you. A 9.2% loan grows faster than a 5.3% loan. Every dollar you send to the 9.2% loan stops that expensive growth. The debt avalanche method exploits this mathematical truth.
Federal graduate loans currently carry an 8.07% interest rate. Undergraduate loans sit at 6.52%. Parent PLUS loans reach 9.07%. These rates vary wildly. The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. exploits that variation. The wider the rate spread, the more you save.
The Debt Avalanche for Student Loans vs. the Snowball Method
The snowball method wins on psychology. A 2016 study in the Journal of Consumer Research found that focusing on smallest balances boosts motivation. People feel progress faster. That motivation keeps them paying.
The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. wins on math. It saves more money. A study by the National Bureau of Economic Research found that consumers who follow the avalanche approach pay down debt about 15% faster than those who do not.
Which method is better? The one you actually finish. The avalanche method rewards discipline. The snowball method rewards emotion. Know yourself before you choose.
The Debt Avalanche for Student Loans in Action: Year One
Year one was painful. I cut my grocery budget to $200 monthly. I sold my car and bought a bike. I picked up weekend shifts at a warehouse. That added $700 monthly. Every extra dollar went to Loan A.
I tracked my progress in a spreadsheet. Watching that 9.2% balance drop felt like winning a war. The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. kept me focused. By month twelve, Loan A was down to $4,200.
Interviews: Real People Using the Debt Avalanche for Student Loans
I spoke with Kevin, a 38-year-old engineer with $94,000 in loans. "The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. was the only method that made mathematical sense to me," he said. "I am an engineer. I trust numbers. The avalanche method is pure math. I saved $16,000 in interest over six years."
I also interviewed Danielle, a 29-year-old pharmacist with $142,000 in debt. "I tried the snowball method first," she said. "I paid off a $3,000 loan and felt great. Then I looked at my 9.5% loan still growing. The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. switched my focus. I saved $23,000."
The Debt Avalanche for Student Loans and Mental Health
Debt stress damages mental health. PubMed research confirms a strong link between debt and symptoms of depression, anxiety, and suicidality. The avalanche method reduces stress through financial control. You know exactly where your money goes. You know it saves the most possible.
The American Academy of Pediatrics reports that 68% of pediatricians had educational debt at residency graduation. Even doctors feel the weight. The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. gives borrowers a measurable plan. Measurable plans reduce anxiety.
Step-by-Step: The Debt Avalanche for Student Loans
Step 1: List all student loans from highest interest rate to lowest.
Step 2: Make minimum payments on every loan. Never miss a due date.
Step 3: Throw every extra dollar at the highest-rate loan. Sell things. Work overtime. Cut subscriptions.
Step 4: When the highest-rate loan dies, roll that payment into the next highest rate.
Step 5: Repeat until every loan is gone. The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. becomes automatic.
The Debt Avalanche for Student Loans: Common Mistakes
Mistake 1: Skipping the emergency fund. Save $1,000 first. Without it, one surprise pushes you back to credit cards.
Mistake 2: Ignoring minimum payments on other loans. Late fees destroy progress.
Mistake 3: Quitting after one slip. Perfection is not required. Persistence is.
Mistake 4: Comparing your timeline to others. The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. runs on your schedule.
The Debt Avalanche for Student Loans: New 2026 Rules
Federal repayment rules changed in 2026. The Repayment Assistance Plan caps payments at 1% to 10% of income. Unpaid interest is waived. The debt avalanche method still works with RAP.
New graduate borrowers face a $100,000 lifetime federal loan cap. Annual borrowing is capped at $20,500. The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. becomes even more important. Higher rates mean bigger savings from smart targeting.
The Debt Avalanche for Student Loans: My Final Numbers
I paid off $68,000 in four years and seven months. The snowball method would have taken five years and three months. The avalanche method saved me $11,400 in interest. It also saved my sanity.
The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. is not magic. It is math. Math does not care about your feelings. Math cares about rates. Trust the math.
Conclusion: The Debt Avalanche for Student Loans Pays Off
The Debt Avalanche for Student Loans: How I saved thousands by targeting the highest interest rate first. transformed my finances. It can transform yours. The method requires discipline. It requires patience. It requires ignoring the emotional pull of quick wins. But the payoff is real. I am proof.
Visit healthyhealthhq.com for free debt payoff calculators and mental health support. We help borrowers choose the right method for their personality and goals.
Interactive Question: What is the highest interest rate on your student loans right now? Share your number in the comments. We respond to every post within 48 hours.
Struggling to balance student loan repayment with your mental health? Let's build a personalized payoff plan for your specific situation. [Click here to book a 1-on-1 financial wellness consultation with HealthyHealthHQ.]
References
American Psychological Association. "Stress in America 2025: Money and Mental Health." 2025.
https://www.apa.org/news/press/releases/stress/2025/money-mental-health
Sinha GR, Viswanathan M, Larrison CR. "Student loan debt and mental health: a comprehensive review of scholarly literature from 1900 to 2019." J Evid Based Soc Work. 2024;21(3):363-393.
https://pubmed.ncbi.nlm.nih.gov/38179674/
Amin-Chaudhry A, et al. "Debt Avalanche versus Debt Snowball: A Comparative Analysis." Southern Economic Journal. 2023;90(2):345-372.
https://onlinelibrary.wiley.com/doi/10.1002/soej.12612
Education Data Initiative. "Average Student Loan Interest Rate (2026): Federal vs Private." September 8, 2026.
https://educationdata.org/average-student-loan-interest-rate
American Academy of Pediatrics. "Financing Your Medical Education." July 31, 2025.
https://www.aap.org
Journal of Consumer Research. "Repayment Concentration and Consumer Motivation to Get Out of Debt." 2016;43(3):460-477.
https://academic.oup.com/jcr/article-abstract/43/3/460/2200459
U.S. Department of Education. "Reimagining and Improving Student Education (RISE)." Federal Register, 2026.
https://www.ed.gov
Consumer Financial Protection Bureau. "Student Loans." 2026.
https://www.consumerfinance.gov/consumer-tools/student-loans/
World Health Organization. "Mental Health: Strengthening Our Response." 2026.
https://www.who.int/news-room/fact-sheets/detail/mental-health-strengthening-our-response
2 thoughts on “The Debt Avalanche for Student Loans: How I Saved Thousands”